

By Mulengera Reporters
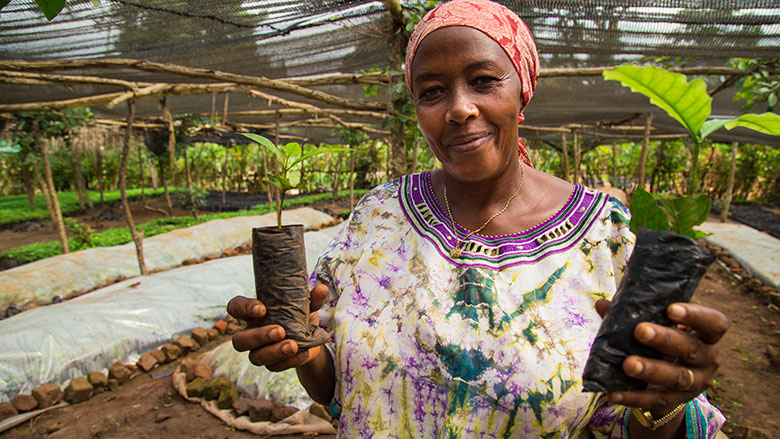
A new independent evaluation of Uganda’s Agricultural Credit Facility (ACF) has exposed a major weakness confronting farmers who borrow under the government-backed scheme — access to reliable and profitable markets for their produce.
The evaluation, conducted by the National Planning Authority (NPA) and released in May 2026, found that seven per cent of surveyed ACF beneficiaries identified limited access to markets for agricultural outputs as a key challenge, raising concerns about whether increased access to credit is translating into sustainable incomes for farmers.
The ACF, administered by the Bank of Uganda since its establishment in 2009, has effectively doubled the volume of credit available to agricultural borrowers, according to the evaluation.
But the findings suggest that getting farmers access to financing is only part of the problem.
For beneficiaries, producing more does not necessarily mean earning more.
The NPA found that even where farmers successfully increase production, many struggle to find reliable markets where they can sell their produce at favourable prices. Some are consequently forced to accept low prices, while others suffer post-harvest losses when produce remains unsold.
The consequences extend beyond farmers’ incomes.
When agricultural products fail to generate sufficient returns, borrowers can find it more difficult to meet their ACF loan repayment obligations. This, in turn, increases the risk of default and could undermine the sustainability of a facility designed to expand agricultural investment.
The findings expose a critical gap in the ACF model: credit can finance production, but it cannot by itself guarantee that farmers will find buyers or receive profitable prices.
For farmers borrowing to invest in improved seeds, machinery, irrigation or other productive assets, the ability to repay ultimately depends on whether those investments generate sufficient income.
Production without profit
The NPA warns that the market challenge has implications for confidence in the entire Facility.
If farmers increase production but see little improvement in their earnings, the incentive to borrow and invest in modern agricultural practices is weakened.
A farmer who struggles to sell produce at a profitable price may become reluctant to take on additional debt, regardless of how affordable the credit is.
This creates a potentially damaging cycle in which access to subsidised financing encourages production, but weak market linkages prevent farmers from converting that production into the income needed to sustain borrowing and investment.
The evaluation therefore points to the need for improved market linkages and greater price stability as critical components of the ACF’s long-term success.
Accountability beyond lending
The findings also raise broader questions about how the performance of the Bank of Uganda-administered Facility is measured.
The NPA noted that while the ACF has generated measurable economic benefits and significantly expanded agricultural credit since 2009, its performance is assessed more through programme-level outcomes than structured governance indicators.
That approach risks overlooking problems experienced by beneficiaries after they receive the money.
The success of an agricultural credit programme cannot be measured only by how much is lent or how many borrowers receive financing. The ultimate test is whether farmers can turn that financing into viable businesses, generate sufficient income and repay their loans without being undermined by factors beyond their control.
For the ACF, the market challenge identified by the NPA suggests that expanding credit must go hand in hand with efforts to connect farmers to dependable buyers and more stable markets.
Otherwise, farmers may continue to face the same contradiction: borrowing more to produce more, only to struggle to sell what they produce profitably.
And for a facility intended to transform agricultural financing, that remains a significant weakness that Bank of Uganda and other policymakers cannot afford to overlook. (For comments on this story, get back to us on 0705579994 [WhatsApp line], 0779411734 & 041 4674611 or email us at mulengeranews@gmail.com).