

By Mulengera Reporters
Pride Bank has taken the Government’s GROW programme into some of Uganda’s most underserved communities, extending affordable credit to women who had previously been locked out of formal finance, including members of the Batwa community in Kisoro, refugees and first-time borrowers.
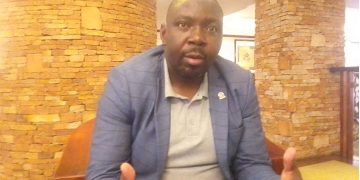
Raymond Ochieng, Manager of Public Sector and GROW Project focal person at Pride Bank, said the government-owned bank has so far disbursed the entire Shs8 billion it received under the project and has already pushed lending beyond the original allocation by recycling repayments from beneficiaries.
“We were given eight billion shillings, and we have disbursed all the eight billion,” Ochieng said. “We have started now using the reflows, the paybacks, and so far we are at 8.6 billion.”
The bank, he said, is now approaching Shs9 billion in cumulative disbursements while awaiting additional funding from the Private Sector Foundation Uganda (PSFU).
The performance marks a substantial expansion beyond Pride Bank’s original target. The institution was initially expected to serve 800 clients across 57 districts, many of which were deliberately selected because they had either never been reached by GROW financing or had limited access to formal financial services.
Instead, Pride Bank says it has already served more than 1,800 clients.
Of these, about 1,200 are new customers to the bank and, significantly, new to formal credit altogether.
For Ochieng, that figure is one of the strongest indicators of the programme’s financial inclusion impact.
“This means that we are financially including those that had never been financially included,” he said.
The bank deliberately targeted remote and underserved areas, including refugee-hosting districts, West Nile, Busoga, parts of Acholi, Teso, Kigezi and Bunyoro. It also expanded into Butambala and Mpigi, which Ochieng said had previously not been served by the programme.
The approach has taken banking services beyond conventional commercial centres and into communities that financial institutions have traditionally considered difficult or costly to serve.
Among the groups benefiting are the Batwa community in Kisoro, one of Uganda’s historically marginalized indigenous communities.
Ochieng said Pride Bank’s Kisoro branch is working to extend financial services to the Batwa as part of the bank’s deliberate strategy to reach people at the “bottom of the economic pyramid.”
“We are serving minority groups, the Batwa in Kisoro,” he said, adding that the bank’s broader purpose is to “transform lives responsibly.”
The bank’s expansion has also reached refugee communities across several parts of the country.
By the time of its reporting, Pride Bank had recorded close to 54 refugees among its beneficiaries and 14 people with disabilities. Ochieng said the actual number of refugees reached had subsequently increased as the bank deepened its operations in refugee settlements.
The bank has been using a community banking model to overcome some of the barriers that refugees face in accessing conventional credit.
Under the model, refugees form groups, guarantee one another and save together, enabling the bank to extend financing based on group cohesion and mutual accountability.
The model has been rolled out in Kyangwali in Kikuube, Madi-Okollo, Rhino Camp, Yumbe, Terego, Obongi and Koboko.
Ochieng said the refugee segment is increasingly becoming an important area of opportunity for the bank, with more partners showing interest in working with Pride Bank as its presence in refugee communities grows.
Another factor behind the rapid uptake has been the bank’s decision to make access to GROW financing more flexible.
Women can access up to Shs10 million without collateral, while loans above that amount require collateral.
According to Ochieng, the flexible arrangement helped overcome one of the biggest barriers facing women entrepreneurs—lack of acceptable collateral—and contributed to a surge in applications.
The initial resistance to the programme was nevertheless significant.
Ochieng said some women in the targeted communities were initially sceptical because they had heard promises about GROW financing before and feared they were being misled again.
But after the first beneficiaries received financing, he said, word spread and women began turning up at Pride Bank branches in large numbers.
The result is now a sizeable pipeline of applicants awaiting the next tranche of funds.
Beyond credit, Pride Bank says the GROW intervention is also producing changes in how women manage their enterprises.
Through financial literacy and business support services, beneficiaries have been assisted to register businesses, formalize operations, maintain proper books of accounts and adopt digital methods of conducting business.
Ochieng said some beneficiaries who previously lacked basic accounting systems are now maintaining proper financial records, while others have formalized businesses that were previously unregistered.
Business formalization, he noted, can also expand the government’s tax base as enterprises become part of the formal economy.
The bank has also observed employment effects among some beneficiaries.
According to Ochieng, some women who previously employed only one person have expanded their businesses to employ as many as five people after receiving financing.
He argues that such changes demonstrate the programme’s intended progression from micro-enterprises towards larger and more sustainable businesses.
Ochieng described GROW as a major intervention in supporting women who already have businesses but lack the capital needed to expand.
He contrasted that model with programmes that may provide financing without the same emphasis on business growth and enterprise development, arguing that government should consider maintaining and strengthening GROW beyond the current World Bank-supported phase.
He also called for a clear government budget to sustain the programme when external financing ends.
“If the World Bank withdraws, the government should be able to provide a comprehensive budget for this particular programme,” he said.
The rapid deployment of funds, however, also highlights the challenge of matching demand with available capital.
Pride Bank has already exhausted its initial Shs8 billion allocation and is relying on repayments to continue lending as it waits for additional funds.
This means the sustainability and scale of the intervention will depend partly on the availability of new capital and the ability of beneficiaries to repay and successfully grow their enterprises.
There are also social challenges surrounding the control and use of women’s business loans.
Ochieng said Pride Bank has not recorded cases of women being subjected to domestic violence because of GROW financing. The bank instead counsels women and engages spouses to encourage families to work together around the loans.
However, the bank has encountered cases where husbands or other family members have attempted to influence how women use the funds.
Its appraisal process, Ochieng said, is designed to identify situations where a woman may simply be borrowing money on behalf of someone else. In such cases, the bank may decline to finance the applicant and encourage alternative financing arrangements.
There have also been cases where families have diverted portions of business loans towards household needs, including school fees or completing homes.
While such diversions violate the intended purpose of the financing, Ochieng said the bank sometimes works with families to establish repayment plans where the expenditure has addressed an urgent household need or reduced another major expense, such as rent.
The bank’s response has therefore combined enforcement of lending conditions with financial counselling and household engagement.
Pride Bank says it has deliberately trained its officers to prepare women and their families before loans are disbursed, with the aim of ensuring that financing does not become a source of conflict.
The emerging picture from Pride Bank is therefore mixed but significant: the GROW programme has moved beyond simply counting loans to reaching communities previously excluded from formal finance, including refugees, persons with disabilities, first-time borrowers and the Batwa community.
Its biggest test now is whether the rapid expansion in access can translate into sustained enterprise growth, employment and improved household incomes—and whether the financing can be maintained at a scale large enough to meet the demand emerging from communities that have only recently entered the formal financial system.
For Pride Bank, the early figures are striking: a Shs8 billion initial allocation has generated Shs8.6 billion in lending through repayments, more than 1,800 clients have been served against an initial target of 800, and about 1,200 beneficiaries are new to both the bank and formal credit.
The challenge ahead is turning that momentum into lasting financial inclusion for Uganda’s most underserved entrepreneurs.